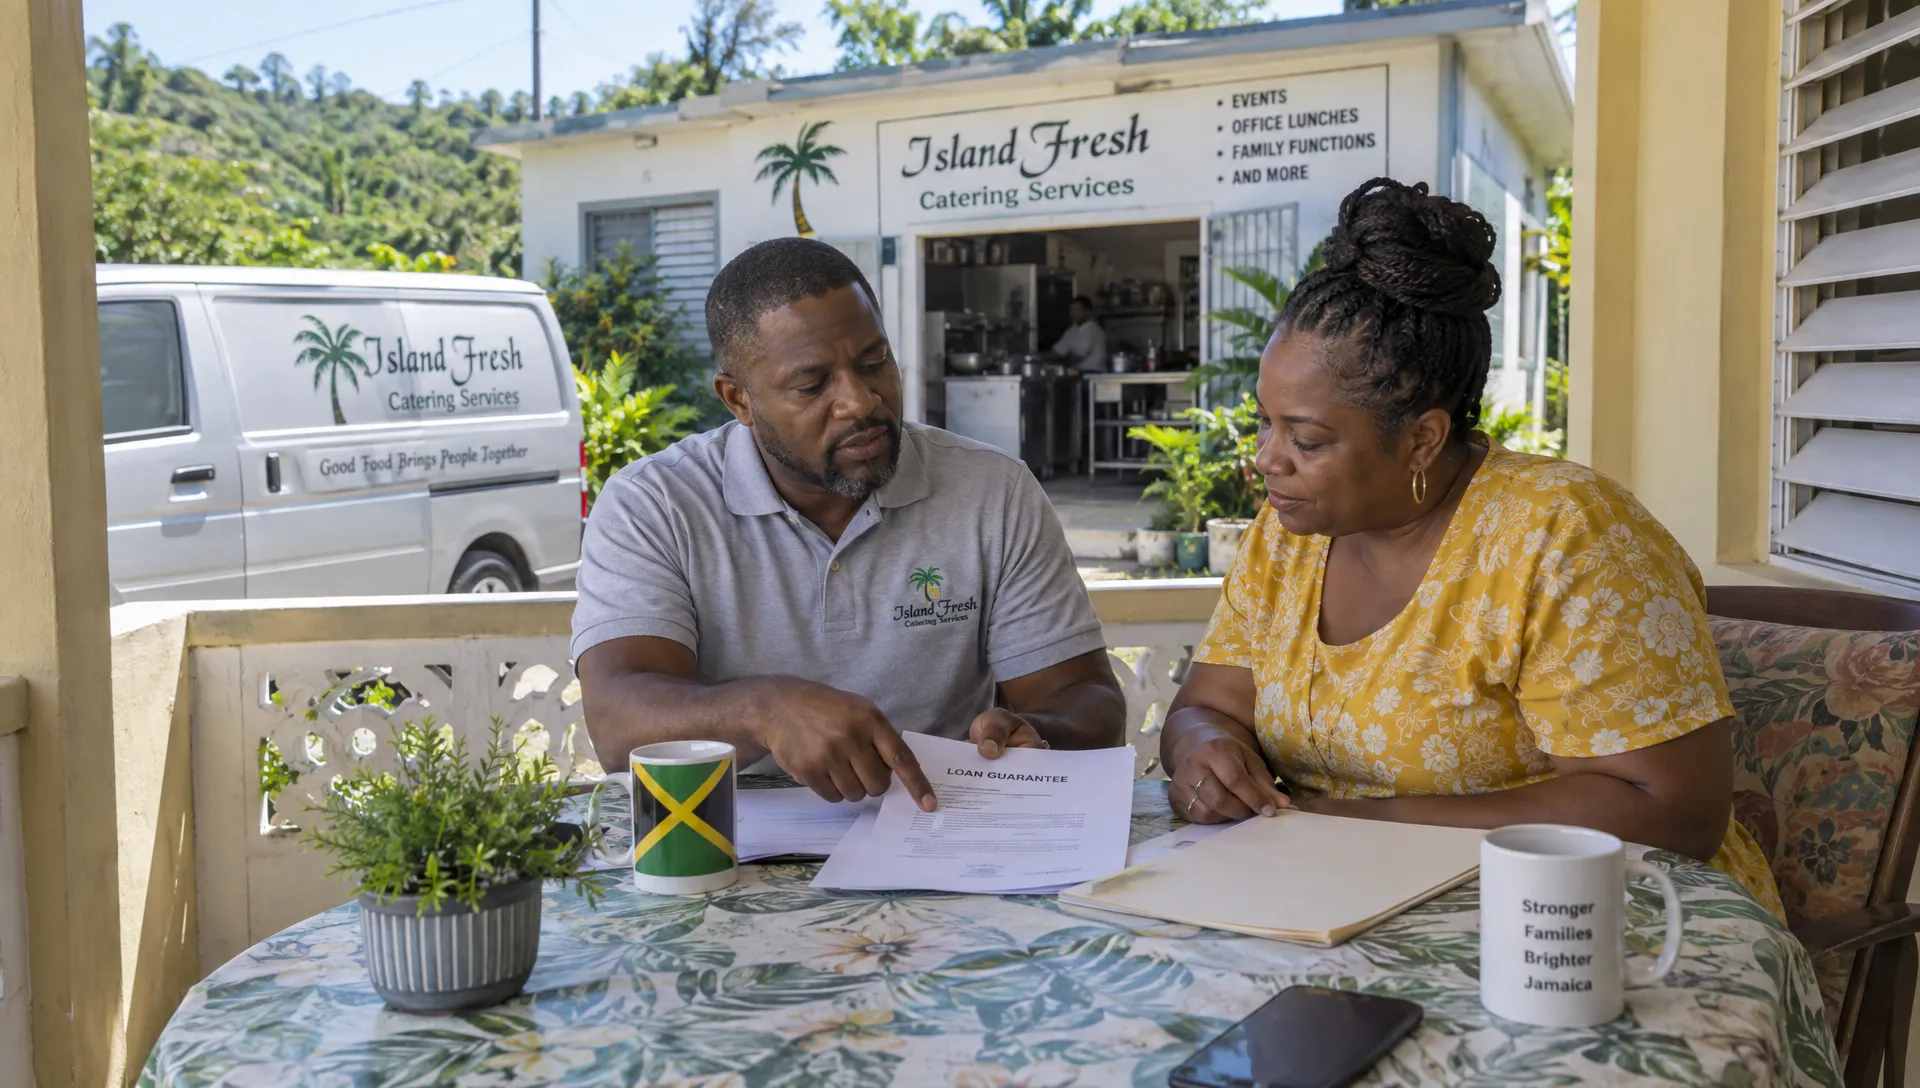
A lender may describe a personal guarantee as a routine requirement, but signing it can put your own finances behind someone else’s debt. Before agreeing, ask an attorney-at-law for legal advice on the actual documents, not just the lender’s explanation. The key questions are how much you could owe, when payment can be demanded and how you can eventually be released.
For Jamaican business owners, directors and relatives supporting a borrower, a guarantee deserves a separate decision from whether the underlying loan is commercially worthwhile.
What a personal guarantee actually changes
A personal guarantee is a contractual promise to answer for another person’s or company’s obligations. If the borrower fails to meet those obligations, the creditor may be entitled to seek payment from you under the guarantee.
The borrower and guarantor have different roles. A company may owe the loan, while a director signs a separate obligation in an individual capacity. The company’s limited liability does not remove that voluntarily assumed obligation. This is an important distinction when considering the personal liability risks facing company directors.
Do not assume the lender must sell the company’s assets or complete proceedings against the borrower before approaching you. The wording may permit a demand against the guarantor without those steps.
Your potential exposure is determined by the documents and applicable law, not by the label “standard guarantee”. A signature block identifying you as a director also does not settle whether you are assuming personal liability elsewhere in the document.
Ask for legal advice before accepting these clauses
Start by identifying the obligations covered. A guarantee supporting one specified loan is different from wording covering every amount a borrower owes the lender, now or in the future.
Clause or wording | Potential effect | Point to clarify |
“All monies” | May cover several obligations rather than one facility | Can it be restricted to a named loan? |
“Continuing guarantee” | May remain effective across transactions or renewals | How can future exposure be ended? |
“Joint and several” | May allow recovery of the covered amount from one guarantor | What is your individual maximum liability? |
Interest and enforcement costs | May increase exposure beyond the loan principal | Are these amounts inside the cap? |
Consent to variations | May permit specified changes without fresh approval | Which changes require your written consent? |
Guarantee and indemnity | May create an additional obligation alongside the guarantee | When can each obligation be enforced? |
An indemnity is not simply another word for a guarantee. Its wording may create a separate obligation to compensate the lender for specified losses, including circumstances in which the guarantee obligation is disputed.
When seeking an attorney’s help for legal advice, ask them to explain both obligations and any waivers of rights or defences. A document headed “Guarantee and Indemnity” should be reviewed as a whole, including definitions and incorporated facility terms.
Understand the difference between a guarantee and security
A personal guarantee does not, by itself, necessarily give the lender a mortgage over your home. Security over property usually involves a separate instrument or additional provisions that must be examined.
That distinction does not make an unsecured guarantee harmless. If a creditor establishes personal liability, enforcement may affect assets through the legal procedures available to it. Where security is also granted, the creditor may have rights against the secured property, subject to the documents and applicable law.
Check whether you are being asked to sign a mortgage, charge or other security document alongside the guarantee. Identify whose property is involved and whether another owner must obtain separate advice or provide consent. Joint ownership should not be treated as either automatic protection or automatic liability for the other owner.
For illustration, a guarantee referring to a J$5 million principal limit may still expose you to additional interest and recovery costs if those amounts sit outside the limit. The headline figure is not necessarily the total amount at risk.
Ask for legal advice on the complete security package so that the guarantee and any property obligations are assessed together.
Negotiate the risk before you sign
A lender may decline proposed changes, but requesting them before signing gives you a clearer basis for deciding whether to proceed. An assurance that the lender “never calls on guarantees” is not a substitute for enforceable limits.
Set a meaningful liability cap
A useful cap states the maximum aggregate amount recoverable from you and explains how interest, fees and enforcement costs are treated. A limit on principal alone may leave substantial additional exposure.
Also ask whether your obligation can be restricted to a particular facility, borrower and purpose. If the business later takes additional borrowing, your guarantee should not cover it unintentionally.
Where several people guarantee the same debt, do not assume each person is liable only for an equal share. Joint and several wording may allow the creditor to pursue one guarantor for the covered amount. Any right to seek a contribution from another guarantor is a separate matter, and that person may be unable to pay.
Agree how the obligation ends
Possible protections include an expiry mechanism, release on repayment of a specified facility or a requirement for written consent before defined changes. The drafting must explain what happens to obligations already incurred.
When you ask for legal advice on proposed amendments, distinguish between protections you can enforce against the lender and reimbursement promises made by the borrower. A borrower’s promise does not itself restrict the lender’s rights.
Bring the full transaction file to your attorney
A guarantee may refer to documents you have not received. Reviewing the signature page alone will not reveal the full arrangement, especially where facility conditions define default, interest or the obligations being guaranteed.
Give your attorney the proposed guarantee, loan or facility agreement, relevant terms and conditions, amendments and any security documents. Include correspondence explaining what the lender requires and any written assurances about limits or release.
Your circumstances also matter. Explain your relationship with the borrower, whether you control the business, whether you benefit from the borrowing and whether you are already guaranteeing other debts. If you are supporting a relative or signing under pressure, say so privately.
Before the consultation, write down the maximum loss you could realistically absorb. That helps separate a legally valid commitment from one that is financially unsuitable for you. Legal review can clarify the obligation, but it cannot make an unaffordable risk affordable.
Allow time for questions and changes rather than arranging the review immediately before a signing appointment. When preparing for legal advice, confirm who the attorney represents and whether you need advice independent of the borrower, another guarantor or the lender. Their interests may differ from yours even if everyone wants the transaction completed.

Leaving the business does not necessarily release you
Resigning as a director, selling your shares or ending a relationship with the borrower does not necessarily terminate a personal guarantee. Your contractual obligation may continue after your involvement ends.
This becomes especially important during a business sale. A buyer’s agreement to take responsibility for company debts may operate between buyer and seller without releasing the seller from obligations owed to the lender. Likewise, appointing a replacement guarantor does not by itself establish that the original guarantor has been discharged.
If the guarantee permits termination by notice, check the required method, recipient and effective date. Termination may stop coverage of future transactions while leaving liability for existing obligations intact. A continuing facility can make that distinction particularly important.
Seek written confirmation from the creditor of any agreed release, identifying the relevant guarantee and the scope of the release. Keep it with the signed transaction documents.
Before a resignation, share sale or refinancing, ask for legal advice on whether the proposed arrangements actually end your exposure. Treat release from the guarantee as a separate completion issue, rather than assuming it follows automatically from your departure.
If a demand has already arrived, act promptly
A demand under a guarantee requires a different review from a proposed agreement. Preserve the demand, signed documents, account statements and relevant correspondence. Note when and how the demand was received, and do not ignore court papers.
An attorney can examine whether the demand meets the contractual requirements, which obligations it covers and how the amount has been calculated. The review may also consider changes to the facility, the effect of any security and potential issues with enforceability. None of these should be assumed to provide a defence without examining the facts.
Do not sign an acknowledgment, replacement guarantee or payment arrangement simply to obtain more time. It may affect your position or create additional obligations.
The borrower’s financial distress also needs separate attention. Understanding what happens when a company cannot pay its debts helps explain why pursuing the company and pursuing a guarantor are different issues. Company insolvency does not automatically cancel the guarantee.
Seek help promptly for legal advice on the demand, any response deadline and your options for disputing liability or negotiating payment.
Frequently asked questions
Can a lender demand payment from me before pursuing the borrower? The guarantee may allow that. Do not assume the lender must first sue the borrower or exhaust its security. The agreement’s demand provisions and applicable law need to be checked.
Does a cap always limit everything I might owe? No. A stated cap may apply only to principal, with interest or costs recoverable separately. Ask whether the proposed limit covers the total amount recoverable under both the guarantee and any indemnity.
Can I cancel a guarantee after signing it? Not simply because you change your mind. The document may provide a termination mechanism, or the lender may agree to a release. Ending future exposure and obtaining release from existing liabilities are different outcomes.
Should I obtain independent advice if I trust the borrower? Yes, trust does not establish the scope of the contract or the borrower’s future ability to pay. Ask for legal advice focused on your interests, particularly where you are supporting a relative, have little control over the business or are being urged to sign quickly.
Have the guarantee reviewed before making the commitment
Henlin Gibson Henlin provides legal services in Jamaica, including banking litigation, commercial litigation and compliance and risk law. If you are considering a personal guarantee, contact Henlin Gibson Henlin to discuss the documents and your circumstances before signing.
The decision should rest on a clear understanding of the maximum exposure, the lender’s rights and the route to release, not simply on whether the loan helps the business today.
This article provides general information, not advice on a particular guarantee or transaction.