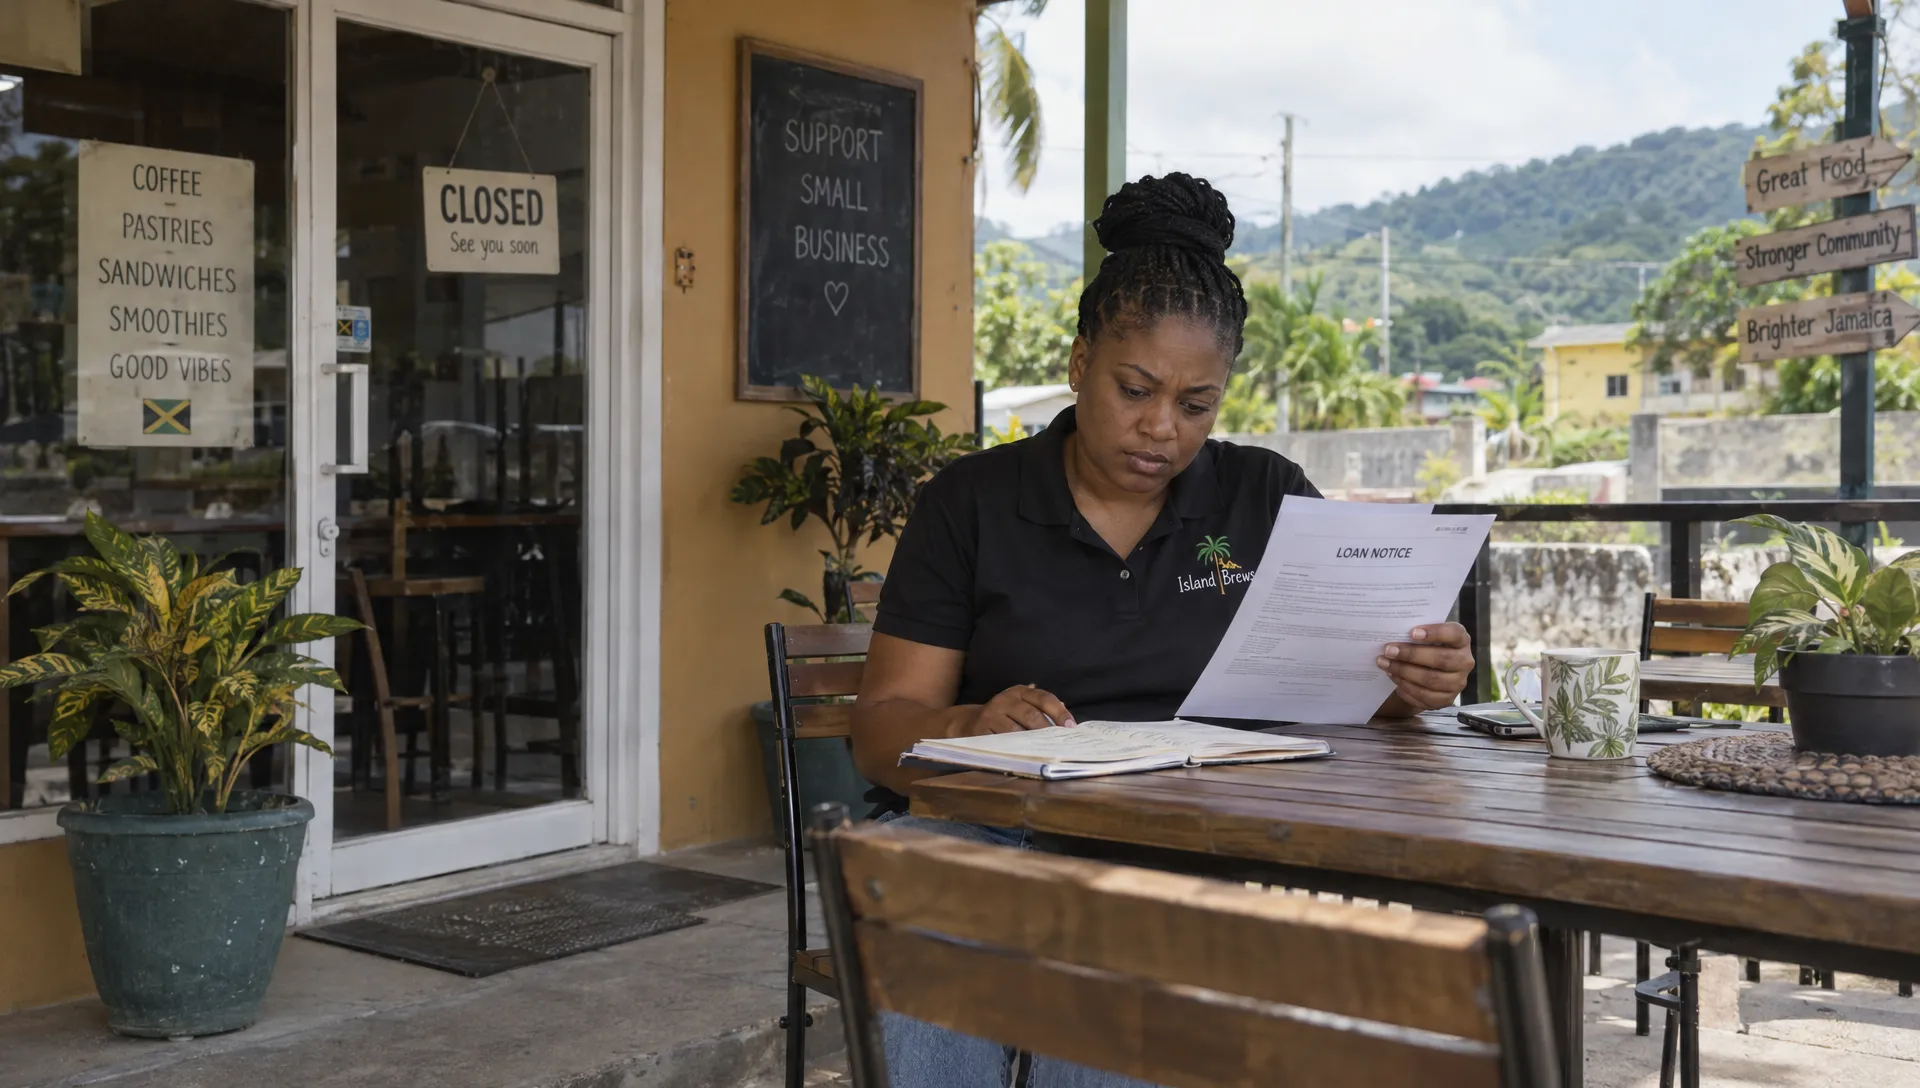
Consult a financial lawyer as soon as a loan looks difficult to service, especially before you sign revised terms, offer additional security or miss a deadline in a lender’s notice. For Jamaican business owners, directors and guarantors, early advice can help distinguish a manageable cash-flow problem from a restructuring that increases personal or business exposure.
A lower monthly instalment is only part of the decision. The revised agreement may extend interest costs, preserve existing defaults or give the lender additional rights over assets.
What loan restructuring actually changes
Loan restructuring changes the terms of an existing borrowing arrangement. Depending on what the lender agrees, it might extend the repayment period, defer principal payments, alter interest terms or replace the repayment schedule.
It is different from refinancing, which generally involves obtaining new borrowing to repay an existing facility. Both require careful review, but restructuring often starts with a lender that already holds security and has contractual rights following default.
A repayment concession is not necessarily a release from default. A lender might accept smaller payments temporarily while reserving its rights over outstanding arrears. Unless the documents address that position, making the revised payments may not resolve the original breach.
The objective should be a legally workable arrangement supported by realistic cash flow, not simply the smallest immediate payment.
When to consult a financial lawyer
You do not need to wait until a bank threatens proceedings. Legal review is useful whenever a proposed solution could change your liabilities, security or ability to operate.
Warning sign | Why legal advice matters |
You expect to miss an instalment | There may be time to negotiate before a payment default occurs |
You have breached a financial covenant | A default can arise even when instalments are current |
The lender requests another guarantee or asset | Short-term relief may create substantial additional exposure |
Several facilities are under pressure | Cross-default clauses may connect otherwise separate loans |
You receive a demand or enforcement notice | The wording, deadlines and available responses need prompt review |
You are asked to sign revised terms immediately | The document may contain acknowledgements, releases or new obligations |
Treat demands and threatened enforcement as urgent
Contact a financial lawyer promptly if the lender demands full repayment, threatens action against collateral or seeks payment from a guarantor. Preserve the notice, its attachments and evidence of when it arrived.
Do not assume that an ongoing conversation with a relationship manager pauses a deadline. Negotiations alone do not suspend contractual obligations, court proceedings or enforcement rights. If time is needed, seek a written agreement identifying which steps the lender will refrain from taking and for how long.
What legal review adds to a repayment proposal
Your accountant can assess whether the business can afford a revised schedule. Your lawyer examines whether the documents deliver that arrangement and what happens if performance falls short.
The review should cover the facility agreement, amendments, security documents, guarantees and relevant correspondence. Particular attention belongs on default clauses, early repayment rights, interest calculations and provisions connecting one facility to another.
It also matters whether the proposed transaction merely varies the existing loan or replaces obligations with a new arrangement. That distinction can affect security, guarantees and documentation requirements.
Where balances or charges are disputed, obtain advice before signing an unconditional acknowledgement of the amount owed. A restructuring document may also include a release of claims against the lender.
Review guarantees before offering more security
A financial lawyer should assess the effect of proposed changes on each guarantor, not just the borrowing company. A director who negotiated the original facility may face a different risk if the revised documents introduce broader wording or additional secured assets.
Check whether a guarantee has a monetary cap, covers future advances or includes a separate indemnity. Do not assume that changing the repayment schedule automatically releases a guarantor, or that an informal assurance limits the signed document.
The borrower’s interests and a guarantor’s interests may diverge. Separate advice can be appropriate, particularly where a family home or jointly owned property is involved. The issues discussed in obtaining advice before signing a personal guarantee remain relevant when an existing guarantee is being reaffirmed or expanded.
Prepare a proposal your lender can assess
A restructuring request is stronger when it explains the problem, quantifies the available cash and offers a credible route back to regular payments.
Bring the following to your initial legal and financial review:
Loan records: Facility letters, amendments, statements, guarantees and security documents.
Lender communications: Default notices, demands, proposed terms and relevant emails.
Financial information: Recent accounts, bank statements and a short-term cash-flow forecast.
Other commitments: Tax liabilities, wages, leases, supplier balances and other borrowing.
A proposed solution: The relief requested, its duration and the evidence supporting repayment afterwards.
Explain whether the difficulty comes from a delayed receivable, loss of a major customer, higher operating costs or a continuing trading loss. Each points towards a different solution. A temporary deferral cannot, by itself, repair a business that consistently spends more than it receives.
Base repayments on cash you can collect
Give your financial lawyer both a realistic forecast and a downside case. If repayment depends on selling an asset or collecting a disputed invoice, identify the uncertainty rather than treating the receipt as guaranteed.
For service businesses, customer payment arrangements also deserve attention. The patient payment options offered by All About Smiles illustrate the kind of arrangement a dental practice might offer. When forecasting your own business’s receipts, establish whether a finance provider pays upfront or customer instalments reach you over time.
Test the proposal against slower collections and essential operating expenses. The lender needs a credible repayment plan, but the business also needs enough working capital to continue trading. Promising payments that leave no room for ordinary disruption can produce another default soon after restructuring.
Compare the full cost and the new default terms
Before accepting revised terms, compare the existing obligations with the proposed arrangement across the whole repayment period.
Proposed change | Potential benefit | Point to check |
Longer repayment period | Lower regular instalments | Total interest and any final balloon payment |
Temporary principal deferral | Immediate cash-flow relief | When principal resumes and how interest is treated |
Capitalising arrears or interest | Less cash required immediately | The increased balance and interest payable on it |
Revised interest rate | Potentially improved affordability | Variable-rate exposure, fees and default interest |
Additional collateral | May support lender approval | Which assets become exposed and when security is released |
Temporary enforcement standstill | Time to negotiate or complete agreed steps | Expiry dates, conditions and rights expressly reserved |
A financial lawyer can translate the agreed commercial terms into specific drafting questions: Are existing defaults waived, temporarily tolerated or left fully enforceable? What triggers acceleration of the revised debt? Does the document require new valuations, insurance or financial reporting?
Ask for the complete proposed documentation before signing. A summary email may not contain the releases, costs clauses or additional obligations included in the final agreement. Confirm who bears legal expenses and whether any filing, registration or other transaction costs apply.

Know when informal negotiations are not enough
Restructuring one loan may be insufficient if the business cannot meet several creditors’ claims or depends on fresh borrowing to cover continuing losses. Directors should seek advice about the company’s wider position rather than focus exclusively on the most vocal lender.
A financial lawyer can help identify when specialist insolvency advice is needed. Jamaica’s Insolvency Act provides formal processes, but their availability and suitability depend on the debtor’s circumstances. Do not assume that requesting a restructuring creates statutory protection or prevents enforcement.
Payments to selected creditors, transfers of assets and new security can require particular scrutiny when insolvency is a concern. Keep reliable records and obtain advice before taking steps intended to place assets beyond creditors’ reach.
For the wider assessment, understanding what happens when a company cannot pay its debts helps distinguish a temporary funding gap from a situation requiring a different legal response.
Choose counsel and agree the scope of work
Look for relevant experience with Jamaican lending documents, security, guarantees and negotiations involving distressed borrowers. Where enforcement has begun, ask whether contentious banking work falls within the proposed engagement.
Check professional standing through Jamaica’s General Legal Council and confirm that the attorney holds a current practising certificate. The lender’s attorney acts for the lender, not for you merely because you are asked to pay that attorney’s costs.
Before instructing a financial lawyer, agree who the client is: the company, an individual borrower or a guarantor. Ask about potential conflicts, especially if several connected parties want joint representation.
Request a written explanation of the fee basis, likely disbursements and initial scope. Document review, negotiation and litigation are different tasks. A staged engagement can help you understand what the first assessment covers and when further work requires approval.
Frequently asked questions
Should I speak to the bank before seeking legal advice? You can notify the lender early that a payment difficulty is emerging. Obtain advice before making binding commitments, admitting a disputed balance or offering additional security. Keep communications accurate and retain copies.
Can a lender refuse to restructure a loan? Generally, a borrower cannot require a lender to accept different commercial terms simply because the existing payments are unaffordable. Contractual rights, applicable law and any relevant formal process need separate assessment.
Will negotiations stop enforcement against my property? Not automatically. Any agreed pause should be documented and checked for its duration, conditions and scope. A court order or statutory protection is a separate matter requiring advice on the particular circumstances.
Can the same lawyer advise the company and its guarantor? Sometimes, but only where professional obligations permit it. Their interests may conflict if a proposal protects the business while increasing the guarantor’s exposure. Disclose the relationships and ask whether independent representation is needed.
Get advice before committing to revised terms
The most useful time to consult a financial lawyer is while there is still time to assess the documents, prepare credible figures and negotiate without an avoidable deadline crisis.
Henlin Gibson Henlin provides banking litigation, commercial litigation and compliance and risk legal services in Jamaica. Contact the firm to discuss your loan documents, proposed restructuring and any immediate deadlines.
This article provides general information, not legal advice. The appropriate response depends on your agreements, financial position and applicable Jamaican law.